
The SIP HCI provides a ranking of the most important healthcare systems in terms of cost for private medical care, as a reflection on the country-specific insurance premiums paid per year for international private medical insurance. The index includes 60 countries and evaluates the country-based premium assessment of seven globally leading international health insurance providers.
Global Ranking – 2026
| Average yearly IPMI based cost (in USD) | |||
|---|---|---|---|
| Rank | National Flag | Country | Cost |
| 1 | 🇺🇸 | United States | 23’987.11 |
| 2 | 🇭🇰 | Hong Kong (SAR) | 19’352.90 |
| 3 | 🇸🇬 | Singapore | 17’612.66 |
| 4 | 🇨🇳 | China | 15’235.36 |
| 5 | 🇬🇧 | United Kingdom | 14’986.58 |
| 6 | 🇦🇪 | United Arab Emirates, Dubai | 12’141.68 |
| 7 | 🇲🇽 | Mexico | 11’769.52 |
| 8 | 🇧🇷 | Brazil | 11’739.43 |
| 9 | 🇧🇸 | Bahamas | 11’398.72 |
| 10 | 🇹🇭 | Thailand | 11’215.39 |
| 11 | 🇹🇼 | Taiwan | 10’931.35 |
| 12 | 🇨🇭 | Switzerland | 10’808.71 |
| 13 | 🇯🇵 | Japan | 10’707.06 |
| 14 | 🇧🇭 | Bahrain | 10’488.78 |
| 15 | 🇶🇦 | Qatar | 10’469.32 |
| 16 | 🇬🇷 | Greece | 10’274.14 |
| 17 | 🇦🇺 | Australia | 10’230.05 |
| 18 | 🇵🇦 | Panama | 9’920.00 |
| 19 | 🇸🇦 | Saudi Arabia | 9’816.66 |
| 20 | 🇨🇱 | Chile | 9’772.98 |
| 21 | 🇪🇸 | Spain | 9’755.20 |
| 22 | 🇹🇷 | Turkey | 9’678.71 |
| 23 | 🇲🇨 | Monaco | 9’649.46 |
| 24 | 🇰🇷 | South Korea | 9’422.60 |
| 25 | 🇨🇴 | Colombia | 9’407.33 |
| 26 | 🇨🇷 | Costa Rica | 9’396.44 |
| 27 | 🇦🇬 | Antigua & Barbuda | 9’379.63 |
| 28 | 🇰🇳 | St. Kitts & Nevis | 9’351.87 |
| 29 | 🇮🇩 | Indonesia | 9’321.42 |
| 30 | 🇬🇩 | Grenada | 9’292.55 |
| 31 | 🇺🇾 | Uruguay | 9’244.68 |
| 32 | 🇨🇦 | Canada | 9’235.44 |
| 33 | 🇨🇾 | Cyprus | 9’160.42 |
| 34 | 🇵🇹 | Portugal | 8’993.39 |
| 35 | 🇮🇹 | Italy | 8’924.68 |
| 36 | 🇫🇷 | France | 8’901.02 |
| 37 | 🇳🇿 | New Zealand | 8’868.21 |
| 38 | 🇰🇼 | Kuwait | 8’820.39 |
| 39 | 🇦🇷 | Argentina | 8’814.16 |
| 40 | 🇧🇪 | Belgium | 8’729.36 |
| 41 | 🇲🇾 | Malaysia | 8’711.85 |
| 42 | 🇦🇿 | Azerbaijan | 8’327.92 |
| 43 | 🇦🇹 | Austria | 8’270.00 |
| 44 | 🇮🇳 | India | 8’205.76 |
| 45 | 🇿🇦 | South Africa | 8’191.89 |
| 46 | 🇩🇪 | Germany | 8’161.78 |
| 47 | 🇵🇭 | Philippines | 8’121.37 |
| 48 | 🇱🇻 | Latvia | 8’113.28 |
| 49 | 🇻🇳 | Vietnam | 8’091.57 |
| 50 | 🇱🇺 | Luxembourg | 8’068.62 |
| 51 | 🇳🇬 | Nigeria | 8’021.88 |
| 52 | 🇪🇬 | Egypt | 7’935.75 |
| 53 | 🇸🇪 | Sweden | 7’862.51 |
| 54 | 🇲🇺 | Mauritius | 7’745.37 |
| 55 | 🇰🇪 | Kenya | 7’712.42 |
| 56 | 🇳🇴 | Norway | 7’653.37 |
| 57 | 🇳🇱 | Netherlands | 7’642.01 |
| 58 | 🇲🇦 | Morocco | 7’609.40 |
| 59 | 🇲🇹 | Malta | 7’591.04 |
| 60 | 🇷🇴 | Romania | 7’518.65 |
Data as at September 2026
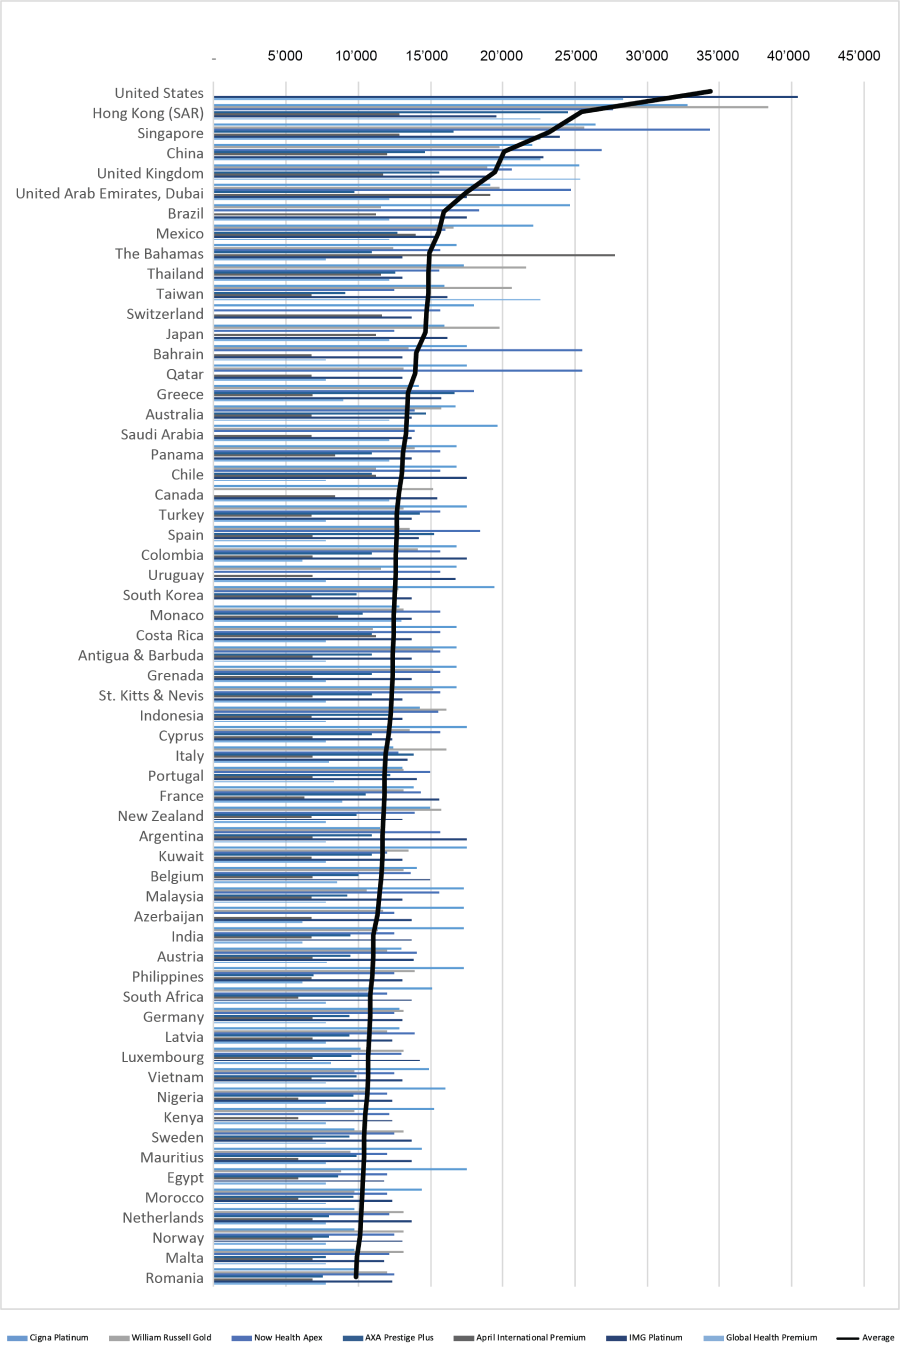
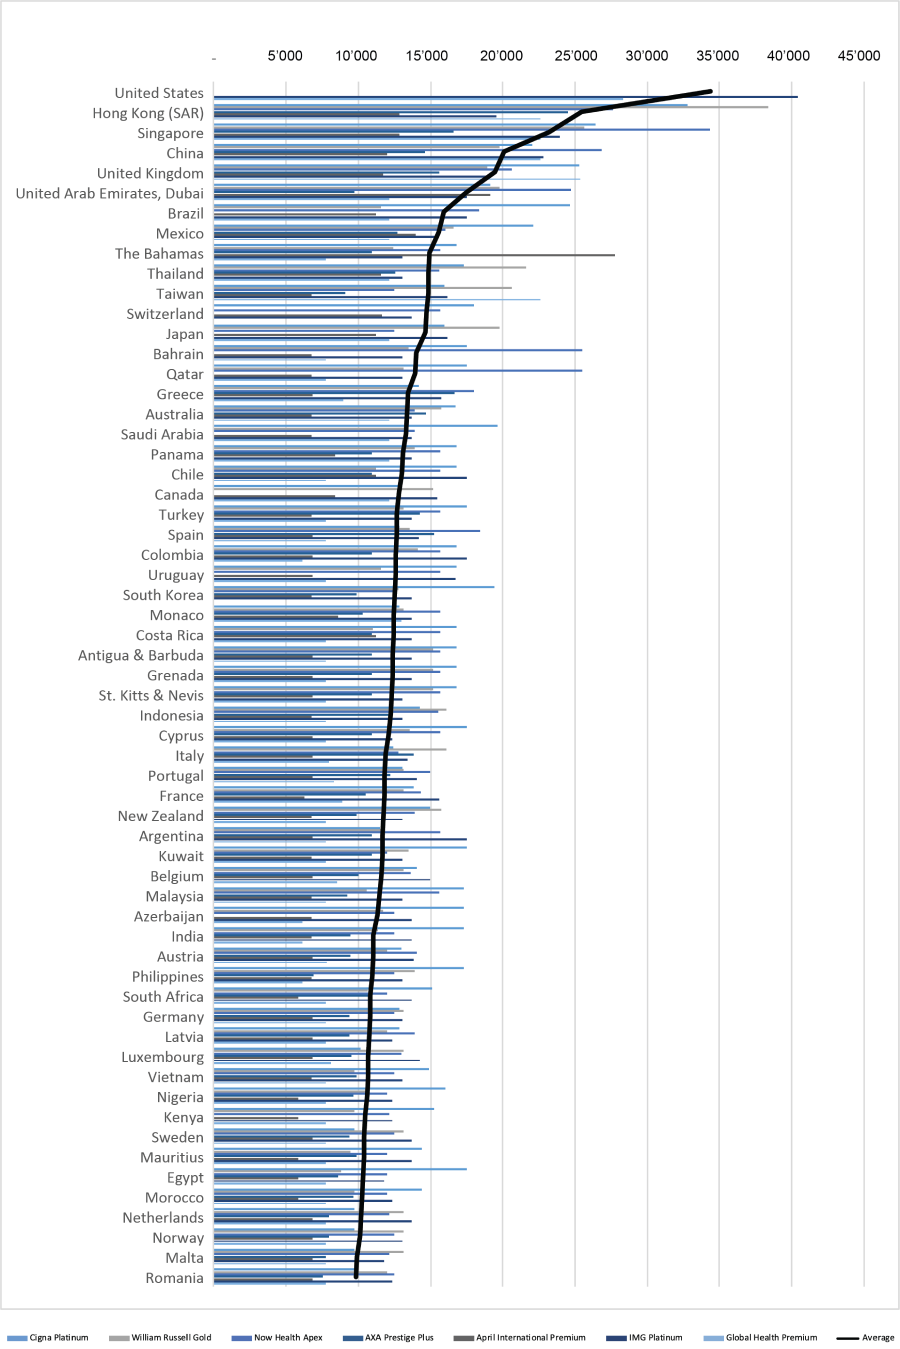
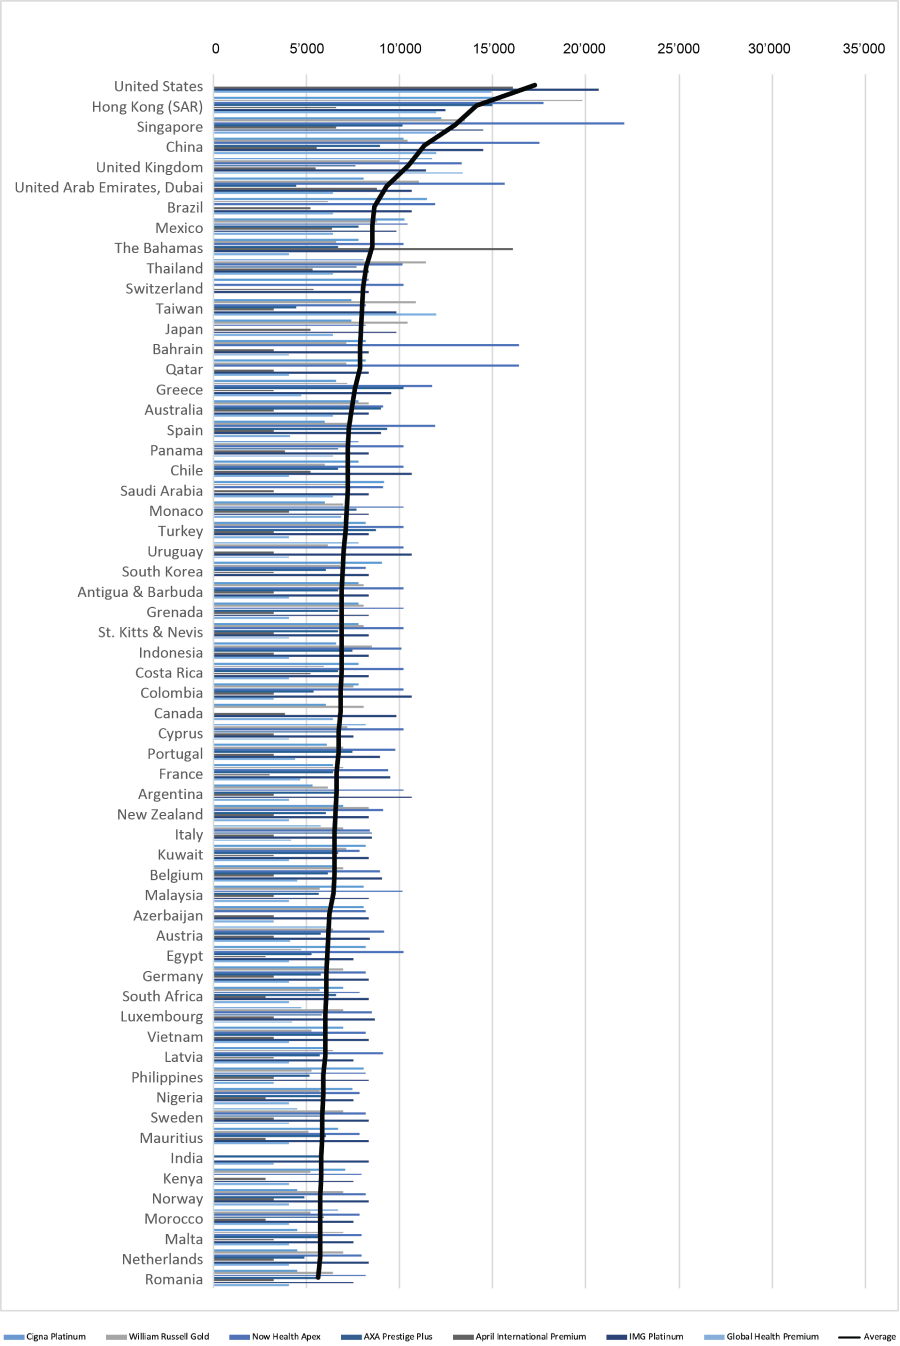
The SIP HCI reflects on the actuarial pricing of seven insurance companies, 60 countries, and three personas with their individual ranking. The individual and cross-persona comparison provides insight into private insurance premium and healthcare cost exposure across different demographics that can be particularly valuable to private individuals, families, and multinational companies when comparing international relocation, insurance, and treatment cost.
This index does not seek to compare insurance premiums and benefits between the referenced international health insurance companies and international health insurance plans. Insurance benefits and services differ between the plans quoted, explaining the differences in premiums for the same persona in the same country. Individual comparison for private individuals or corporate international health insurance should be sought, requiring additional personal information and personal insurance demands and needs to identify the best cover or optimize existing cover.
Persona 1 Ranking – 2026
Persona 2 Ranking – 2026
Persona 3 Ranking – 2026
The SIP Health Cost Index provides more than a snapshot of the global pricing of private healthcare and medical insurance at a single point in time. Comparing the year-on-year results reveals how the cost landscape is evolving across countries and regions, highlighting markets where healthcare costs are accelerating, stabilising, or diverging from global trends.
Year-on-year movements are influenced by a combination of factors, including medical inflation, healthcare utilisation, provider pricing, advances in treatment, regulatory developments and changing insurer claims experience. Looking beyond headline rankings provides important context for understanding what is driving changes in the global pricing of private healthcare and medical insurance.
This section explores some of the most notable trends and observations emerging from the SIP HCI 2026. It examines regional patterns, significant year-on-year movements, and developments that may shape the cost of accessing high-quality private healthcare in the years ahead.
The Most Expensive Countries
The upper end of the SIP Health Cost Index shows considerable stability. The five most expensive markets remain unchanged from 2025: the United States, Hong Kong (SAR), Singapore, China and the United Kingdom. This consistency suggests that the concentration of high private healthcare costs in these markets is structural rather than the result of short-term fluctuations. All five combine sophisticated private healthcare infrastructure with comparatively high treatment costs and strong demand for state-of-the-art medical services.
The United States remains a clear outlier. With an average annual IPMI cost of approximately USD 24’000, it remains substantially more expensive than Hong Kong, ranked 2nd at around USD 19’350, and Singapore, ranked 3rd at USD 17’600. The gap between the United States and the other leading markets illustrates the exceptional cost exposure associated with US private medical care. At the same time, the relatively narrow range between Hong Kong, Singapore, and China indicates the emergence of a distinct cluster of high-cost Asian private healthcare markets.
The most significant development near the top of the ranking is the United Arab Emirates, represented by Dubai, which ranks as the 6th most expensive healthcare market out of the 60 assessed countries. Its rise brings Dubai increasingly close to the established group of the world’s most expensive private healthcare markets. This development is particularly noteworthy given the UAE’s continued expansion as an international healthcare destination and its large internationally insured population. While movements in cost and ranking can reflect multiple factors, this suggests that the private healthcare environment in Dubai warrants particularly close observation in the future.
Global Medical Inflation
The SIP Health Cost Index 2026 suggests substantial medical inflation across the globe. Its methodology of working with standardised profiles across countries and years (the British, 35-year-old persona used in 2025 remains aged 35 for the analysis in 2026) allows direct comparison of the expected cost for a person of the same age at different points in time and therefore a comparison of global pricing of private healthcare and health insurance without age adjustments.
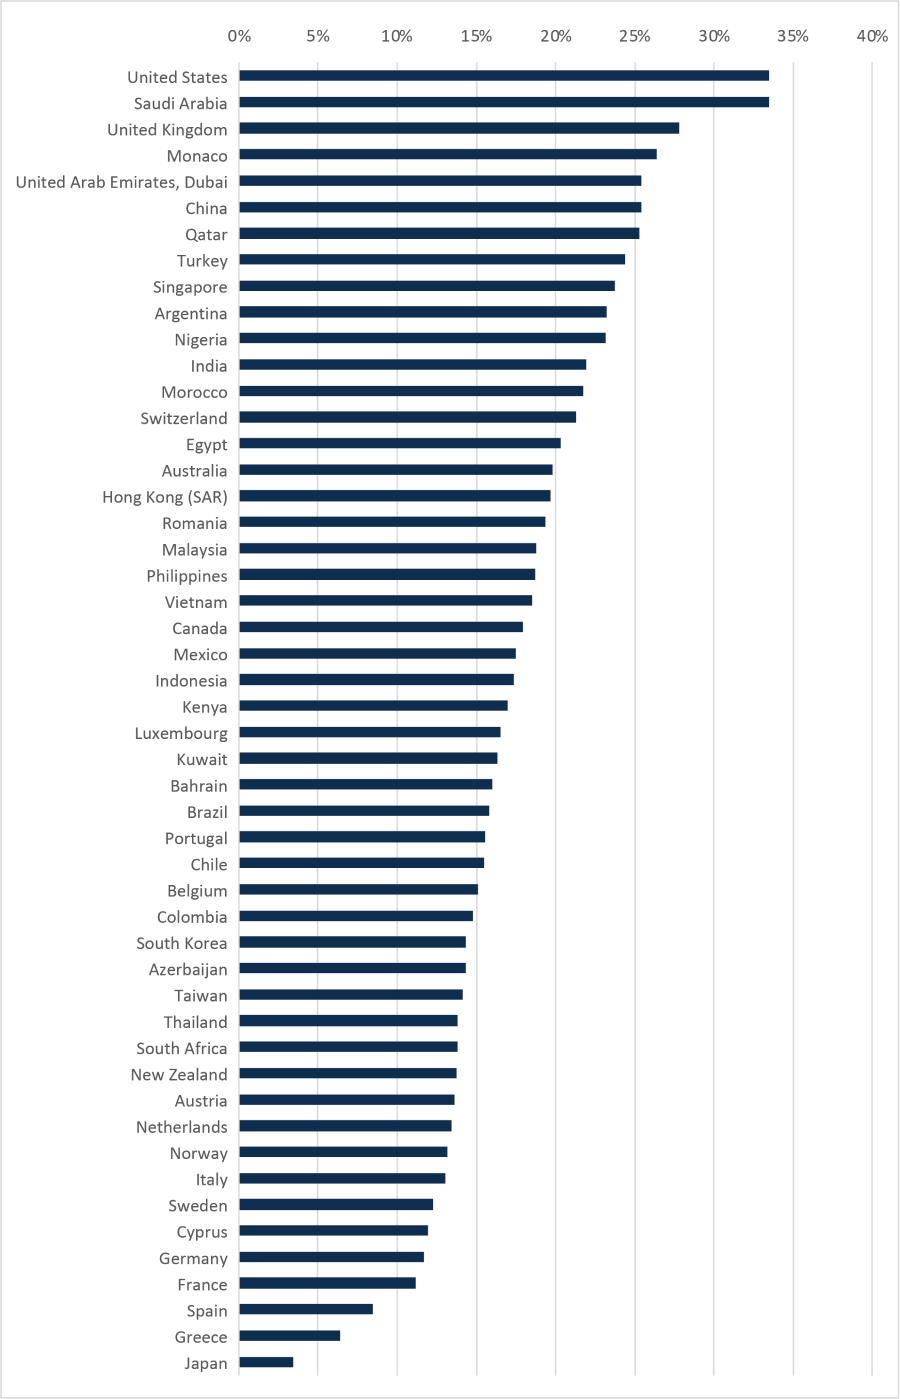
Across all countries included in both 2025 and 2026, the indicated private healthcare and health insurance costs have increased. Costs for the same standardised profiles increased by an average of 18%, indicating that rising costs are not confined to individual healthcare systems or regions but represent a widespread global phenomenon. The magnitude of the increases nevertheless varies considerably. At the upper end, the United States and Saudi Arabia recorded increases of approximately 33%, followed by the United Kingdom at 28%, Monaco at 26%, and China and the UAE at 25%. Turkey, Singapore, Nigeria and Argentina also recorded increases exceeding 20%. At the other end of the spectrum, Japan increased by only 3% and Greece by 6%, while Spain, Malaysia and France remained below 12%.
Importantly, these changes should not be interpreted as a direct measure of underlying medical price inflation alone. IPMI premiums reflect a broader combination of hospital and physician charges, treatment utilisation, advances in medical technology, pharmaceutical costs, claims frequency and severity, regulatory developments, insurer-specific claims experience and insurance administration costs. Nevertheless, an average increase of 18% is significant: it suggests that the cost of financing comprehensive private healthcare is rising considerably faster than general consumer inflation in many markets.
Regional Insights
The report reveals pronounced regional differences in the expected cost of international private medical insurance, used as a proxy for private healthcare costs, and the pace at which costs are increasing. While inflation is evident across almost all markets, the data does not point towards uniform global convergence. Instead, distinct regional patterns reflect differences in healthcare pricing, utilisation, private-sector development and underlying regulatory and policy norms.
Africa
Africa remains the least expensive region globally, with all six markets positioned in the lower third of the global ranking. Nigeria is the region’s most expensive market, followed by South Africa and Egypt. Despite comparatively low absolute costs, inflationary pressure remains significant: Nigeria recorded a 23% year-on-year increase and Egypt 20%, while South Africa increased by 14% and Kenya by 17%. This illustrates that lower-cost healthcare markets are not insulated from the broader inflationary pressures affecting international medical insurance.
Asia
Asia remains one of the world’s most expensive regions for private healthcare. Three Asian markets, Hong Kong (SAR), Singapore and China, occupy positions two, three and four globally. Their year-on-year increases are substantial, ranging from 20% in Hong Kong to 25% in China. Yet Asia is far from homogeneous. Japan recorded an increase of only 3%, the lowest among all comparable markets, while Malaysia increased by 19% and India by 22%. The region therefore combines some of the world’s highest-cost healthcare markets with considerable variation in underlying cost trends.
Europe
Europe is the largest and one of the most diverse regional groups in the SIP HCI 2026. The United Kingdom remains a significant outlier, ranking 5th globally and recording a 28% year-on-year increase. Switzerland ranks 12th out of 60, following a 21% increase. Across the continent, however, cost trends vary substantially. Turkey recorded an increase of 24% and Monaco 26%, compared with only 6% in Greece and 8% in Spain. This dispersion suggests that there is no single European medical inflation trend, but rather that individual healthcare systems, provider pricing, utilisation patterns and local insurance market dynamics continue to produce markedly different cost trajectories across the region.
Middle East
The Middle East shows particularly strong upward momentum. Dubai moved four positions to 6th globally, accompanied by a 25% year-on-year increase, while Saudi Arabia recorded one of the largest increases in the entire SIP HCI at 33%. Qatar also recorded significant increases. These developments suggest that the Gulf is becoming increasingly important within the global private healthcare landscape.
North America
North America presents the widest internal cost disparity, largely because of the United States. With an average annual IPMI cost approaching USD 24’000, the USA remains the most expensive market globally and recorded a further 33% increase over 2025. Canada, by comparison, ranks 32nd and recorded an 18% increase. The Bahamas is relatively expensive at approximately USD 11’400, while Antigua & Barbuda, St. Kitts & Nevis and Grenada cluster around USD 9’300. All pricing for these island countries is conducted without consideration that healthcare may be sought in the United States, which would significantly increase the expected healthcare costs.
Oceania
Oceania occupies the middle of the global ranking. Australia ranks 17th with an average cost of approximately USD 10’230 and recorded a sizeable 20% year-on-year increase. New Zealand ranks considerably lower at 37th, with average costs of approximately USD 8’870 and a more moderate 14% increase. The difference between the two markets widened further in 2026, illustrating that even geographically proximate and broadly comparable developed healthcare systems can follow different private healthcare cost trajectories.
South America
South America, as defined within the SIP HCI, contains several markets in the upper-middle part of the global ranking. Mexico and Brazil stand out at 7th and 8th globally, with average annual costs of approximately USD 11’770 and USD 11’740, respectively. Mexico recorded a 17% year-on-year increase and Brazil 16%. Further down the ranking, Chile, Colombia and Argentina recorded increases of 16%, 15% and 23%, respectively. The results indicate broad-based cost pressure across the region, while also showing a meaningful cost divide between Mexico and Brazil and the region’s remaining markets.
Healthcare Policy and Regulation Implications
The SIP Health Cost Index 2026 suggests that healthcare policy and regulation play a significant role in determining not only the absolute cost of private healthcare, but also the rate at which those costs increase. Countries with greater regulatory control over healthcare pricing tend to show lower medical insurance inflation, while countries relying more heavily on private-market pricing tend to exhibit either the highest premium levels, the fastest premium growth, or both. Japan provides the clearest example, with an increase of just 3%, while Greece, Spain, France and Germany also remain below many of the higher-growth markets.
By contrast, more market-driven healthcare systems can expose insurers to greater variability in healthcare costs. The United States represents the most pronounced example, combining the highest average cost in the Index with a 33% year-on-year increase. It is a market with very limited governmental healthcare cost control, where healthcare providers set their own pricing. Instead of government policy regulating pricing, health insurance companies establish sophisticated medical networks with contractually agreed medical fees to manage healthcare costs.
A further policy challenge is emerging in rapidly developing healthcare markets. Saudi Arabia, India, Nigeria, United Arab Emirates and China recorded increases of more than 20%, despite most not yet being among the world’s most expensive markets. Expanding private healthcare capacity, increasing utilisation and broader insurance penetration may place upward pressure on costs where cost-management mechanisms are still developing.
These findings should not be interpreted as establishing a direct causal relationship between regulation, private healthcare cost and private medical insurance premiums. Nevertheless, they highlight an important policy consideration: healthcare affordability depends not only on expanding access and medical capacity, but also on how effectively healthcare systems manage the prices and utilisation associated with that growth. For governments, insurers and employers, cost containment may therefore become an increasingly vital component of maintaining sustainable access to high-quality private healthcare.
Global Wealth Migration and Private Healthcare Costs
The geography of global wealth is changing, with internationally mobile high-net-worth individuals increasingly concentrating in a relatively small number of attractive financial and lifestyle destinations. Interestingly, several prominent HNW relocation hubs also feature among the higher-cost markets in the SIP Health Cost Index. Hong Kong and Singapore rank 2nd and 3rd globally, while the United Arab Emirates, the United Kingdom, Switzerland, Monaco and the Bahamas all record comparatively high costs for international private medical insurance.
Many of these markets have developed sophisticated private healthcare ecosystems serving affluent domestic populations, expatriates and internationally mobile families. This can include premium private hospitals, internationally trained specialists, advanced diagnostics and cross-border treatment networks. An increasing concentration of affluent residents may further strengthen demand for such services and support continued investment in high-end healthcare infrastructure. At the same time, a population with greater ability and willingness to pay for healthcare may be less price-sensitive, potentially contributing to higher utilisation and provider pricing.
While not consistent across all countries, the overlap between major wealth destinations and higher-cost private healthcare markets raises an important consideration: as wealth becomes increasingly mobile, demand for premium healthcare may increasingly migrate with it.
The SIP Health Cost Index (SIP HCI) is a data-driven tool that compares healthcare cost levels across a carefully curated selection of countries. Unlike traditional indexes that are based on national healthcare spending or public healthcare costs, this index focuses on the true cost expectations in private healthcare for globally mobile individuals and families.
The index benchmarks countries based on the cost of International Private Medical Insurance (IPMI). As the preferred health insurance class for executives, wealthy families, and global citizens, IPMI is provided by international insurance companies operating globally, with insured individuals domiciled across multiple jurisdictions. This enables insurers to generate meaningful and comparable insights into what individuals pay for private healthcare in different countries.
IPMI premiums are primarily priced based on the expected healthcare costs in a specific country. However, they also reflect the reality that privately insured individuals may seek medical care abroad due to limitations in local healthcare quality or the absence of specific procedures and diagnostic capabilities in their home country.
Within the SIP HCI, the cost of international private medical insurance is assessed for multiple personas in each country and compared across selected insurance providers. The average cost of private medical insurance in a country serves as a reliable reference point for the underlying healthcare cost level. By incorporating actuarial pricing data from several leading global insurers, the index reduces the impact of outliers in markets where individual insurers may have limited data, thereby ensuring a more robust and balanced country ranking.
Personas
For the analysis, three distinct personas were selected to reflect varying demographic, socioeconomic, and healthcare-related profiles. The selection captures diversity across age, gender, and nationality, allowing for comparative insights into expected healthcare costs.
Each persona represents a typical individual within their respective demographic group. This differentiation supports a more nuanced interpretation of the data and enhances the relevance of the findings across population segments.
The personas remain the same as used in the SIP HCI 2025. As a consequence, the personas’ date of birth is adjusted (e.g. from 1990 to 1991), in order to keep the same age. This allows the difference in premiums between two consecutive years of the SIP HCI to be compared using the same personas. Variations in premiums are therefore not a result of a change in age, but rather of medical inflation and actuarial pricing adjustments made by the insurer.
The SIP Health Cost Index (SIP HCI) is based on the following three personas.
- Persona 1
- Date of birth: 01.01.1991 – 35 years
- Sex: Male
- Nationality: British
- Persona 2
- Date of birth: 01.01.1976 – 50 years
- Sex: Female
- Nationality: American
- Persona 3
- Date of birth: 01.01.2002 – 24 years
- Sex: Female
- Nationality: Indian
Country selection
The SIP HCI covers 60 countries selected based on their relevance to expat executives and affluent individuals. This is based on public data and research such as the Wealth Migration research reports by Henley & Partners, as well as proprietary SIP data.
The countries newly added to the SIP HCI 2026 are Mauritius, Malta, Latvia, Grenada, St. Kitts & Nevis, Antigua & Barbuda, the Bahamas, Panama, Costa Rica and Uruguay.
| Region | Countries |
|---|---|
| Africa | Nigeria, Morocco, South Africa, Egypt, Kenya, Mauritius |
| Asia | Hong Kong (SAR), Singapore, China, Japan, Taiwan, Thailand, Indonesia, Philippines, Malaysia, India, South Korea, Vietnam |
| Europe | United Kingdom, Turkey, Switzerland, Greece, Monaco, Cyprus, France, Spain, Portugal, Belgium, Italy, Austria, Germany, Luxembourg, Netherlands, Sweden, Norway, Romania, Malta, Latvia |
| Middle East | Saudi Arabia, Azerbaijan, Qatar, United Arab Emirates, Bahrain, Kuwait |
| North America | United States, Canada, Grenada, St. Kitts & Nevis, Antigua & Barbuda, the Bahamas |
| Oceania | New Zealand, Australia |
| South America | Brazil, Mexico, Colombia, Chile, Argentina, Panama, Costa Rica, Uruguay |
Insurer selection
The selected insurance providers that serve as reference points for the SIP Health Cost Index (SIP HCI) meet a number of criteria to ensure reliability. These include the reputation of the insurer, as well as the availability of high-quality insurance plans that minimise out-of-pocket costs, which are not reflected in actuarial pricing.
In addition, insurers must operate on a truly global scale, offering their insurance plans in the majority of the evaluated countries, with differentiated pricing that reflects variations in healthcare costs across jurisdictions.
This index does not aim to compare pricing between individual insurance providers. Where differences in pricing for similar products exist, this does not necessarily indicate that one insurer offers a superior proposition. Variations may result from differences in insurance benefits, areas of coverage, service levels, or medical network arrangements with healthcare providers.
Cigna Global
Cigna Global is part of The Cigna Group, a leading global health-services company that serves over 170 million customers and patients in more than 200 countries and territories. Headquartered in Bloomfield, Connecticut, the parent group operates worldwide with regional offices across Europe, Asia, the Middle East, and the Americas, and employs around 73’500 people.
Cigna Global specialises in international private medical insurance, offering flexible, modular plans designed for expatriates, globally mobile individuals, and high-net-worth individuals. Its proposition is distinguished by a strong global medical network, 24/7 multilingual customer service, commitment to comprehensive preventive care cover, and its strong proposition for those who wish to have USA cover included.
For the SIP HCI, the following insurance plan was used, ensuring the most comprehensive cover with the lowest possible personal risk retention and out-of-pocket expenses.
- Insurance plan: Platinum
- Area of cover: Worldwide, excluding USA (including USA for country of residence United States)
- Coverage: Inpatient, outpatient, maternity, preventive medicine, dental, vision, evacuation, repatriation
- Deductible: USD 0
- Payment frequency: Annual
- Policy structure: Core module, outpatient module, evacuation & crisis assistance plus module, health & wellbeing module, vision & dental module
- Specialty: Nationality may impact the premium
William Russell
William Russell is an independent international insurance provider founded in 1992, headquartered in Lightwater, Surrey, United Kingdom. The company has built a strong reputation as a boutique provider in the international private health insurance space.
William Russell specialises in international private medical insurance, complemented by life and income protection products tailored for expatriates and globally mobile clients. Its plans are available to private individuals and companies in more than 160 countries.
For the SIP HCI, the following insurance plan was used, ensuring the most comprehensive cover with the lowest possible personal risk retention and out-of-pocket expenses.
- Insurance plan: Gold
- Area of cover: Regional coverage zone
- Coverage: Inpatient, outpatient, maternity, preventive medicine, dental, evacuation, repatriation
- Deductible: USD 0
- Payment frequency: Monthly
- Policy structure: Core cover, increased cover for emergency medical evacuation, increased cover for wellbeing, routine dental, complex dental
- Specialty: Pricing based on coverage zones
Now Health International
Now Health International is a specialist international health insurer founded in 2010, with headquarters in Hong Kong and regional offices in Beijing, Shanghai, Singapore, Jakarta, Dubai, and the United Kingdom. The company employs over 300 people and serves more than 100’000 members across 200 countries and territories.
Now Health International focuses exclusively on international private medical insurance, offering flexible plans for individuals, families, and corporate clients through its WorldCare and SimpleCare product ranges. Its proposition combines comprehensive global coverage with digital innovation and high service standards. In many countries, Now Health can also insure local nationals.
For the SIP HCI, the following insurance plan was used, ensuring the most comprehensive cover with the lowest possible personal risk retention and out-of-pocket expenses.
- Insurance plan: Apex
- Area of cover: Worldwide, excluding USA
- Coverage: Inpatient, outpatient, maternity, preventive medicine, dental, vision, evacuation, repatriation
- Deductible: USD 0
- Payment frequency: Annual
- Policy structure: Core cover, extended evacuation module, wellness, optical and vaccination – Option 2 module
- Specialty: China premium converted from RMB to USD
AXA Global Healthcare
AXA Global Healthcare is part of AXA Group, one of the world’s largest insurance organisations, serving millions of clients globally. Headquartered in London, United Kingdom, with offices in Paris, Dubai, Hong Kong, and Dublin, AXA Global Healthcare focuses exclusively on international private medical insurance for individuals, families, and corporate groups living or working abroad.
Backed by the financial strength and global presence of the AXA Group, the company offers flexible, modular health plans that provide access to an extensive worldwide medical network. Its proposition is distinguished by 24/7 multilingual customer service, digital claims management, and a strong emphasis on preventive care, mental wellbeing, and holistic health support.
For the SIP HCI, the following insurance plan was used, ensuring the most comprehensive cover with the lowest possible personal risk retention and out-of-pocket expenses.
- Insurance plan: Prestige Plus
- Area of cover: Worldwide, excluding USA
- Coverage: Inpatient, outpatient, maternity, preventive medicine, dental, vision, evacuation, repatriation
- Deductible: USD 0
- Payment frequency: Annual
- Policy structure: Core cover
- Specialty: n/a
April International
April International is part of the APRIL Group, an independent French insurance services company founded in 1988 and headquartered in Lyon, France, with regional offices in Paris, London, United Kingdom, Cologne, Germany, Hong Kong, Singapore, Bangkok, Ho Chi Minh City, and Mexico City. The group employs over 2’400 people worldwide and serves clients in more than 180 countries.
April International specialises in international health insurance solutions for expatriates, globally mobile individuals, and corporate clients, combining the strength of a global network with local expertise. Its health plans are known for their flexibility, ranging from emergency-only to comprehensive coverage, and cater to both individuals and groups.
For the SIP HCI, the following insurance plan was used, ensuring the most comprehensive cover with the lowest possible personal risk retention and out-of-pocket expenses.
- Insurance plan: Elite
- Area of cover: Worldwide, excluding USA (including USA for country of residence United States)
- Coverage: Inpatient, outpatient, maternity, preventive medicine, dental, vision, evacuation, repatriation
- Deductible: USD 0
- Payment frequency: Annual
- Policy structure: Core cover, outpatient module, dental/optical module, maternity module
- Specialty: April International completely restructured their insurance plans for 2026. The area of cover is no longer offered in zones, but now is either worldwide, or worldwide excluding USA.
International Medical Group (IMG)
International Medical Group (IMG) is a global insurance and assistance provider founded in 1990, headquartered in Indianapolis, Indiana, USA, with key offices in Miami, Florida, USA, Dublin, Shanghai, and the United Kingdom through its acquisition of ALC Health. IMG is part of SiriusPoint.
IMG offers international private medical insurance, travel medical insurance, and emergency assistance services to expatriates, travellers, and organisations across more than 190 countries. Its proposition is distinguished by combining insurance coverage with integrated medical assistance, evacuation coordination, and claims services. The combination of IMG’s scale, capabilities, and the legacy of ALC Health enables localised service within a robust global platform.
For the SIP HCI, the following insurance plan was used, ensuring the most comprehensive cover with the lowest possible personal risk retention and out-of-pocket expenses.
- Insurance plan: Platinum
- Area of cover: Worldwide, excluding USA (including USA for country of residence United States)
- Coverage: Inpatient, outpatient, maternity, preventive medicine, dental, vision, evacuation, repatriation
- Deductible: USD 0
- Payment frequency: Annual
- Policy structure: Core cover, dental cover level USD 2’000 module, maternity cover level USD 20’000 module
- Specialty: n/a
Global Health
Global Health, established in 2014 and previously known as Foyer Global, is the international health insurance division of Foyer S.A., Luxembourg’s largest private insurer, founded in 1922. Today, Global Health provides global private medical insurance across more than 180 countries worldwide.
Global Health specialises in international private medical insurance for expatriates, globally mobile individuals, families, and corporate clients, offering simple and transparent insurance plans with no annual policy limit. Coverage includes inpatient, outpatient, dental, maternity, and preventive care.
For the SIP HCI, the following insurance plan was used, ensuring the most comprehensive cover with the lowest possible personal risk retention and out-of-pocket expenses.
- Insurance plan: Premium
- Area of cover: Worldwide, excluding USA (including USA for country of residence United States)
- Coverage: Inpatient, outpatient, maternity, preventive medicine, dental, vision, evacuation, repatriation
- Deductible: USD 0
- Payment frequency: Monthly
- Policy structure: Core cover, additional assistance module
- Specialty: Premiums converted from EUR to USD
Local Insurance and Taxes
Where an insurer offers locally compliant insurance solutions (for example, in Dubai, UAE), the locally compliant product equivalent is calculated. In some countries Insurance Premium Tax must be applied by insurers, increasing the premium of international private medical insurance in addition to the cost of healthcare. The countries where such taxation applies are listed below:
| Country | IPT |
|---|---|
| Austria | 1.0% |
| Belgium | 9.25% |
| France | 14.0% |
| Greece | 15.0% |
| Italy | 2.5% |
| Luxembourg | 4.0% |
| Portugal | 7.5% |
| Spain | 0.15% |
| UK | 12.0% |
For the calculation of premium costs in the SIP HCI, these taxes are added.
All rights reserved. The SIP monogram, SIP Medical Family Office logo, and related brand assets are exclusively owned trademarks. All other trademarks, service marks, and logos used in this index are the property of their respective owners.
No part of this index may be reproduced in any form or by any means without the prior written permission of SIP Medical Family Office. Although the material contained in this index has been prepared based on information from public and private sources believed to be reliable, no representation, warranty, or undertaking, expressed or implied, is given as to the accuracy of the information contained herein. SIP Medical Family Office expressly disclaims any liability for the accuracy and completeness of the information.
This index does not seek to compare insurance premiums and benefits between the referenced international health insurance companies and plans. Insurance benefits and services differ between plans, which explains variations in premiums for the same persona within the same country. Individual comparisons for private or corporate international health insurance should always be conducted, requiring specific personal information, as well as individual insurance needs and preferences, to determine the most suitable or optimised coverage. No information in this index guarantees that insurance plans are available in all listed countries.
This index is distributed for general informational and educational purposes only and does not constitute any form of advice. It should not form the basis of any decision. The information contained herein does not constitute an offer to sell or a solicitation of an offer to buy, nor should it be interpreted as such, with respect to any product or service. SIP Medical Family Office is not responsible for the content of external websites or information resources referenced in this index.
The information in this index is believed to be accurate as of the date of publication but is subject to change without notice. SIP Medical Family Office has no obligation to provide updates or revisions in the event of changing circumstances. Neither SIP nor its affiliates, employees, or agents shall be liable for any loss or damage whatsoever, including but not limited to direct, indirect, special, incidental, or consequential damages, arising from or in connection with the use of, or reliance on, this information.
All information is provided “as is” without any representations or warranties of any kind, express or implied, including but not limited to completeness, accuracy, reliability, suitability, or availability for any purpose.
Note: The SIP Health Cost Index 2026 was published on 1 October 2026 by SIP Medical Family Office AG, Baarermattstrasse 10, 6340 Baar/Zug, Switzerland; Email mfo@sip.ch.